Short answer: Every divorce involving a home creates mortgage decisions — refinancing to remove one spouse, buyouts, new-purchase financing for the departing spouse, or the sale-and-split. Yet almost no loan officers specialize in this segment. Those who do build a referral engine that attorneys, mediators, and realtors send business to for years. CDS training gives MLOs the cross-disciplinary vocabulary to be that trusted specialist.
Why This Segment Is Underserved
Divorce mortgage work has unique challenges — income qualification when spousal support is in flux, credit implications of joint accounts, timing constraints from court orders, and the emotional complexity of clients making decisions under stress. Most MLOs default to standard qualification checklists that don’t account for these dynamics, which means clients often get told “no” when a specialist could have said “yes with a different structure.”
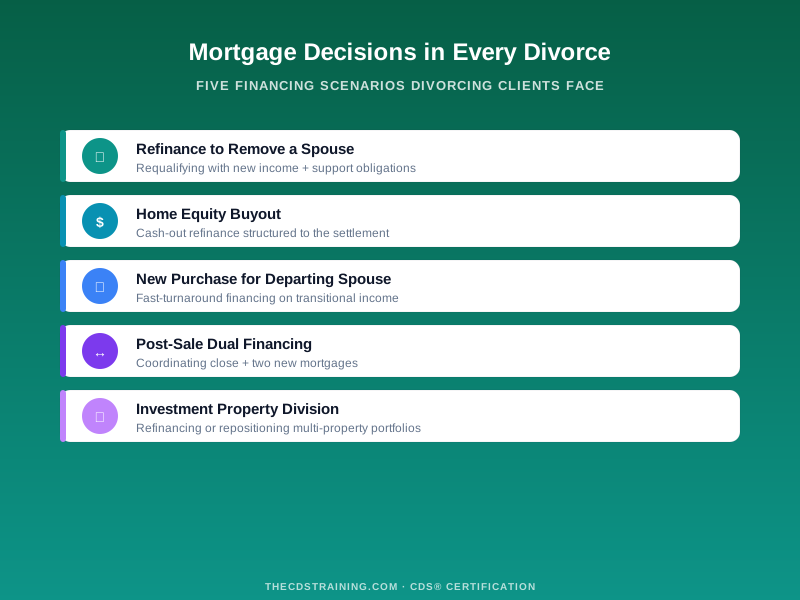
The Mortgage Decisions in Every Divorce
1. Refinancing to Remove a Spouse
When one spouse keeps the home, they typically need to refinance to remove the other spouse from the mortgage and title. Qualifying alone often means overcoming reduced income, court-ordered support obligations, and equity buyout financing all at once.
2. Home Equity Buyouts
The departing spouse’s share of home equity often needs to be financed through the refinance itself — cash-out refinancing structured around the settlement agreement. This requires the MLO to coordinate closely with the attorney drafting the settlement.
3. New-Purchase Financing for the Departing Spouse
The spouse leaving the marital home needs new financing quickly — often within days of the divorce being finalized. Their income picture, credit, and debt situation may all be in transition.
4. Post-Sale Financing
When the marital home sells, both spouses may need new financing simultaneously. Coordinating the sale close with two new purchase mortgages is a specialty skill.
5. Investment Property and Second Home Division
Higher-asset divorces often involve multiple properties. Each property may need its own refinancing or new financing based on which spouse retains it.
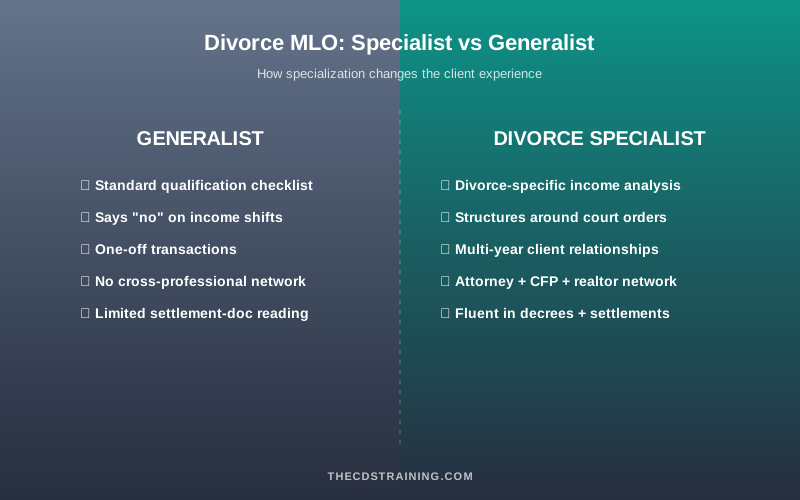
What Makes an MLO a Divorce Specialist
Income Analysis Depth
Understanding how spousal support, child support, and settlement payments affect qualifying income.
Timing Coordination
Managing pre-approval to close so the mortgage aligns with the divorce decree timeline.
Document Navigation
Reading and applying divorce decrees, separation agreements, and court orders to the loan file.
Referral Network
Working alongside attorneys, financial planners, and realtors who trust you to close deals cleanly.
Why CDS Training Fits Loan Officers
The CDS curriculum gives MLOs the same shared vocabulary as attorneys, financial planners, and realtors on the divorce team. That’s exactly what generates high-quality referrals — attorneys refer to MLOs they trust to speak their language and structure loans that fit within the divorce settlement.
Building a Divorce Mortgage Practice
Related reading: divorce cases every family-law attorney sees and building a divorce practice as a financial planner.
Serve the Divorce Mortgage Market
See how CDS training equips loan officers to serve the underserved divorce segment.